Running a cleaning business without knowing your break-even point makes it difficult to tell whether your monthly revenue target is actually enough.
You may be booking more jobs and increasing sales while still struggling to produce consistent profit.
Your break-even point gives you a clearer threshold:
How much revenue does your cleaning business need to generate before it starts making a profit?
This guide explains how to calculate your cleaning business break-even point, convert it into a practical job target, and understand how pricing and costs can move that target.
What Is the Break-Even Point in a Cleaning Business?
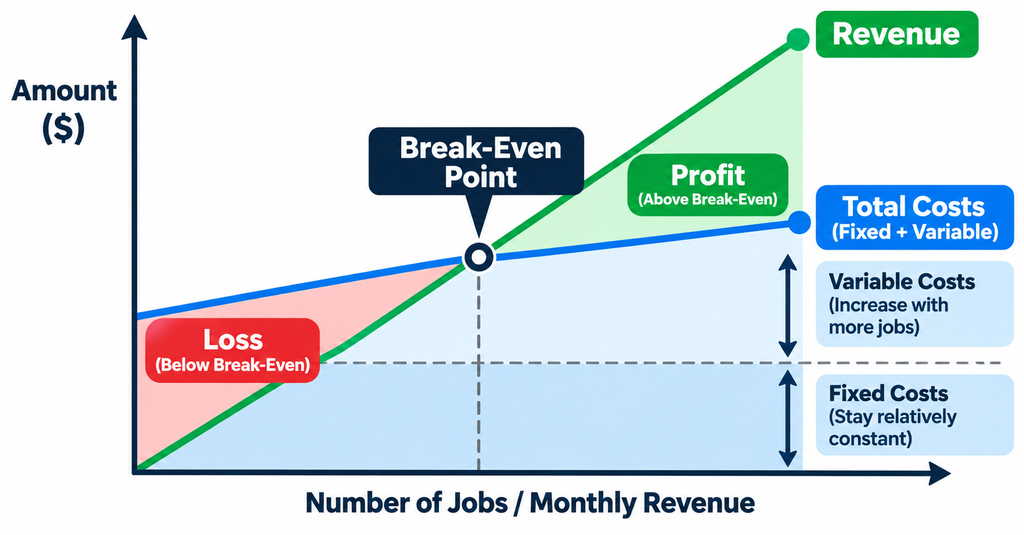
The break-even point is where your revenue covers your business costs.
At break-even:
Revenue = Total Costs
Below that point, the business is operating at a loss.
Above it, the additional contribution generated by your jobs can begin producing profit.
For a cleaning business, the calculation becomes especially useful when you separate costs into two groups:
- Fixed costs that do not change directly with each cleaning job
- Variable costs that rise as you perform more work
FIGURE 1 — HOW THE CLEANING BUSINESS BREAK-EVEN POINT WORKS
Break-even does not mean your business is highly profitable.
It is the threshold where the costs included in your calculation are covered. Your goal should normally be to operate comfortably above break-even, not simply reach it.
Cleaning Business Break-Even Calculator
Use the calculator below to estimate the monthly revenue and number of cleaning jobs required to reach break-even.
The calculator is designed as a planning tool. Your result will only be as useful as the cost assumptions you enter, so use recent business data whenever possible.
The Three Numbers You Need
A practical break-even calculation can start with three inputs.
| Input | What It Means | Examples |
|---|---|---|
| Fixed Costs | Costs that do not directly rise with each additional job | Software, insurance, office expenses, base administrative costs |
| Variable Cost % | The portion of revenue consumed by costs that change with service volume | Direct labor, payroll-related costs, supplies, job-related expenses |
| Average Job Value | Average revenue generated by a completed job | Recurring cleaning, deep cleaning, commercial service |
These numbers allow you to estimate both the revenue threshold and the approximate number of jobs needed to reach it.
Fixed Costs vs. Variable Costs
Separating costs correctly is one of the most important parts of break-even analysis.
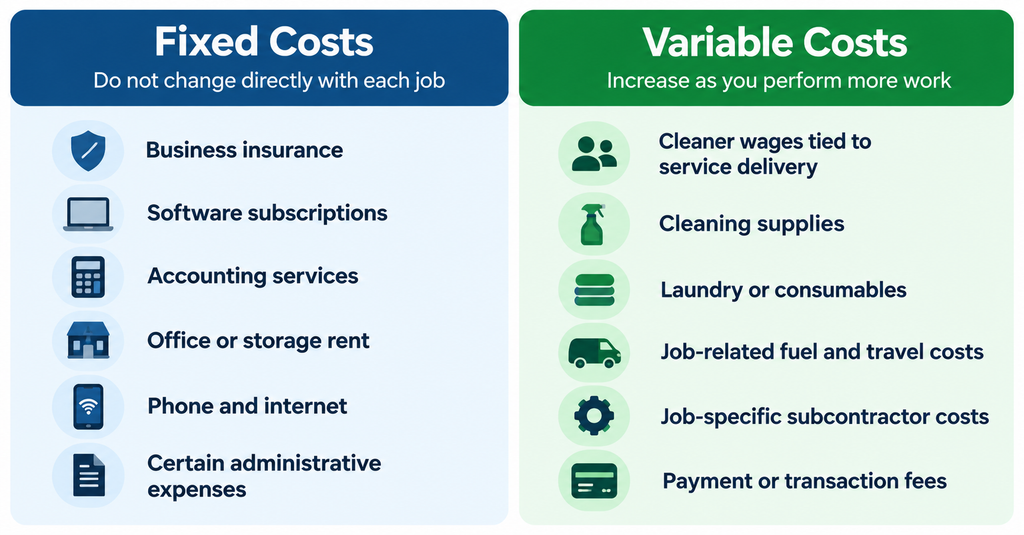
Fixed Costs
Fixed costs generally remain relatively stable within a normal operating range even when the number of cleaning jobs changes.
Examples may include:
- Business insurance
- Software subscriptions
- Accounting services
- Office or storage rent
- Phone and internet
- Certain administrative expenses
Variable Costs
Variable costs increase as the business performs more work.
Depending on how your company operates, these may include:
- Cleaner wages tied to service delivery
- Payroll-related costs
- Cleaning supplies
- Laundry or consumables
- Job-specific subcontractor costs
- Certain payment or transaction fees
Some expenses do not fit perfectly into one category.
For example, vehicle costs, management payroll, or equipment expenses may contain both fixed and variable components. The objective is not to force every expense into a perfect category—it is to use a consistent method that reflects how your costs actually behave.
FIGURE 2 — FIXED COSTS VS VARIABLE COSTS
Contribution Margin Comes Before Break-Even Revenue
You cannot calculate a useful revenue break-even point from fixed costs alone.
First, determine how much of each revenue dollar remains after variable costs.
The basic formula is:
Contribution Margin % = 100% − Variable Cost %
That remaining percentage contributes toward fixed costs first.
Once fixed costs have been covered, additional contribution can begin supporting profit.
Contribution margin is not the same as net profit margin.
Contribution margin focuses on revenue after variable costs. Net profit accounts for the broader expenses of operating the business.
How to Calculate Break-Even Revenue
Once you know your contribution margin, the revenue calculation is:
Break-Even Revenue = Fixed Costs ÷ Contribution Margin %
The important relationship is simple:
Higher fixed costs increase the amount of revenue you need.
Higher variable costs reduce contribution margin and also increase the amount of revenue required.
FIGURE 3 — FROM REVENUE TO BREAK-EVEN
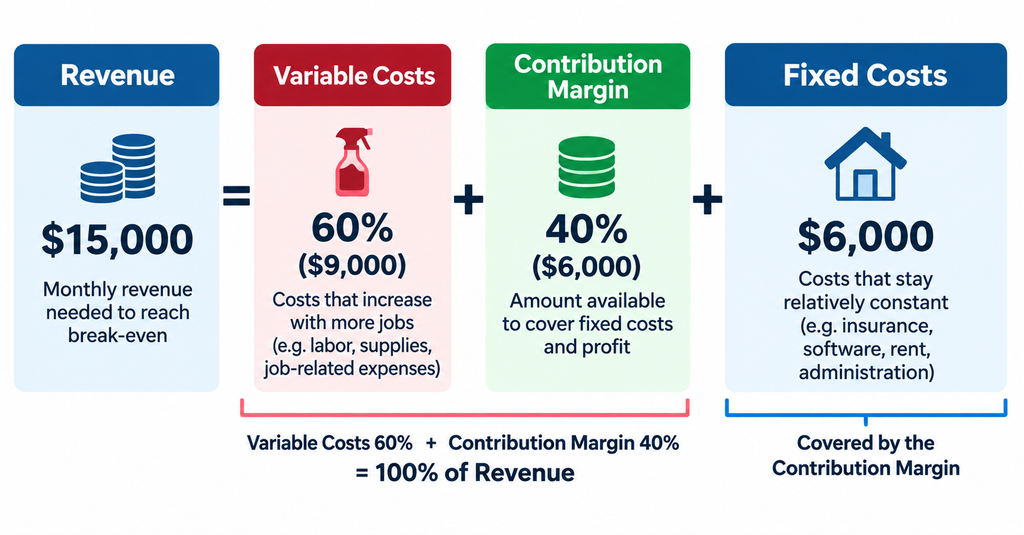
This is why two cleaning businesses with similar monthly expenses can have very different break-even revenue targets.
Their cost structure matters.
Convert Break-Even Revenue Into Jobs
A monthly revenue target becomes easier to manage when you translate it into an approximate number of completed jobs.
Use:
Break-Even Jobs = Break-Even Revenue ÷ Average Job Value
This creates an operational target rather than leaving break-even as an abstract dollar amount.
But treat the result as an estimate.
If your business has several service types with very different prices, one company-wide average job value may hide important differences.
1. Pricing Can Move Your Break-Even Job Target
Pricing affects break-even in more than one way.
A higher price can increase average job value, which may reduce the number of jobs needed to generate a given amount of revenue.
But the effect on profitability depends on what happens to the costs required to deliver the service.
FIGURE 4 — SAME COST STRUCTURE, DIFFERENT JOB TARGET
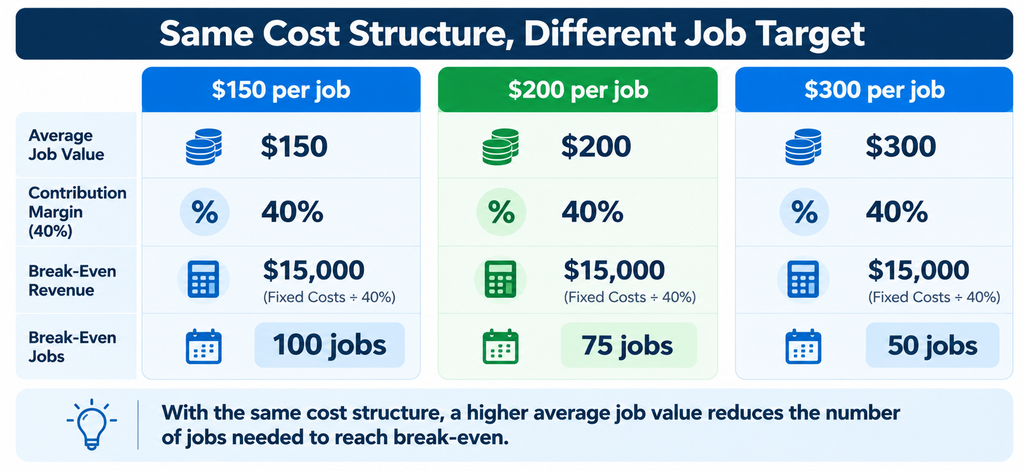
A price increase that adds revenue without a proportional increase in variable cost can improve contribution per job.
That is more useful than increasing prices while simultaneously adding enough labor, supplies, or service scope to consume the additional revenue.
2. Watch What Happens When Variable Costs Rise
Cleaning businesses are labor-intensive, so changes in direct labor economics can materially affect break-even.
If variable costs consume a larger share of revenue, less contribution remains to cover fixed costs.
The business must then generate more revenue to reach break-even.
This can happen even when monthly fixed expenses have not changed.
That is why rising revenue alone does not necessarily mean the business is becoming financially stronger.
3. Fixed-Cost Growth Should Have a Purpose
Adding software, office space, management staff, vehicles, or other infrastructure can increase fixed costs.
That is not automatically a problem.
Some fixed-cost investments can create capacity, improve customer experience, reduce administrative work, or support future growth.
The important question is whether the business can generate enough additional contribution to justify the higher break-even threshold.
Before adding a meaningful recurring expense, estimate how much it changes the revenue required each month.
4. Use Break-Even Analysis Before Hiring
Hiring can affect both capacity and cost structure.
Before adding another employee, estimate:
| Question | Why It Matters |
|---|---|
| What additional labor cost will be created? | Shows the new cost burden |
| How much service capacity will be added? | Estimates potential revenue capacity |
| Is there enough demand to use that capacity? | Reduces idle labor risk |
| Will scheduling or supervision costs change? | Captures secondary costs |
| What happens to break-even revenue? | Shows the new financial threshold |
A new hire can be valuable even if break-even rises—provided the additional capacity can generate enough profitable work.
5. Do Not Confuse Break-Even Revenue With Cash Flow
A business can appear to reach accounting break-even and still experience cash pressure.
Timing matters.
Customers may pay after work is completed while payroll, supplies, rent, insurance, and other obligations may need to be paid earlier.
Break-even analysis tells you about the relationship between revenue and costs.
It does not tell you exactly when cash enters or leaves your bank account.
Break-even answers “How much do we need to generate?”
Cash flow answers “When does the money actually arrive and leave?”
You need both views to operate safely.
6. Calculate Break-Even by Service Type When Needed
A single company-wide break-even calculation is useful for planning, but it can hide differences between services.
For example, recurring residential cleaning, deep cleaning, move-out cleaning, and commercial cleaning may have different:
- Prices
- Labor requirements
- Supply costs
- Travel requirements
- Contribution margins
When those differences are significant, compare services separately.
| Service Metric | What to Compare |
|---|---|
| Average Revenue | Revenue generated per job |
| Variable Cost | Cost that changes with service delivery |
| Contribution per Job | Amount available after variable costs |
| Labor Hours | Capacity required |
| Contribution per Labor Hour | Contribution relative to labor capacity |
This helps identify whether a service is contributing enough to justify the capacity it consumes.
7. Build a Margin of Safety Above Break-Even
Operating exactly at break-even leaves very little room for problems.
Cancellations, unexpected overtime, equipment replacement, customer losses, seasonal demand changes, or unusually high supply costs can quickly push results below the threshold.
A useful additional metric is your margin of safety:
Margin of Safety = Actual Revenue − Break-Even Revenue
You can also express it as a percentage:
Margin of Safety % = (Actual Revenue − Break-Even Revenue) ÷ Actual Revenue × 100
FIGURE 5 — BELOW BREAK-EVEN, BREAK-EVEN, AND PROFIT ZONE
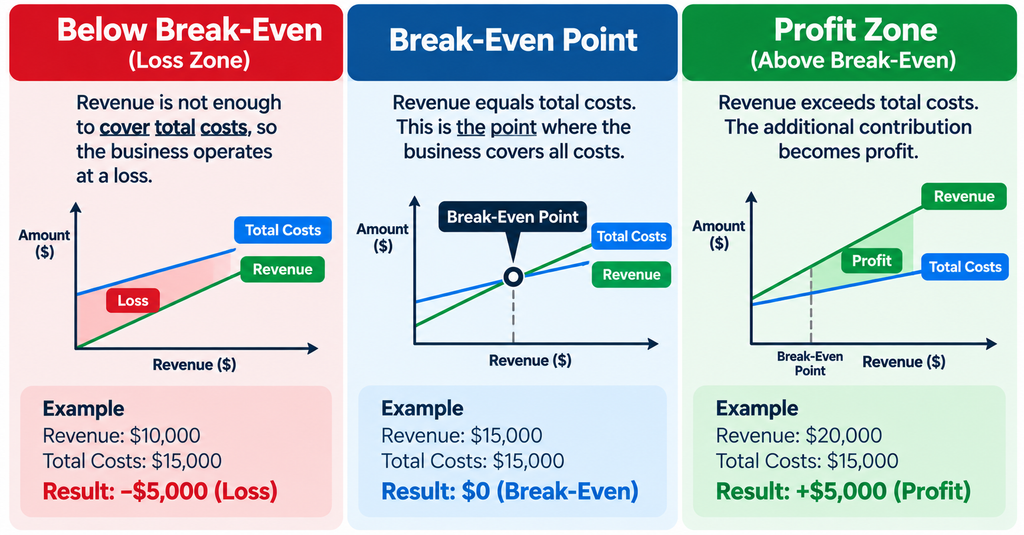
The larger the sustainable gap above break-even, the more room the business has to absorb normal fluctuations.
8. Recalculate Break-Even as the Business Changes
Your break-even point is not permanent.
Recalculate it when meaningful changes occur, such as:
| Change | Possible Effect |
|---|---|
| Wage Increase | Higher variable costs |
| Price Increase | Higher revenue and potentially stronger contribution |
| New Software | Higher fixed costs |
| New Office or Storage | Higher fixed costs |
| Route Improvement | Potentially lower operating waste |
| Service Mix Change | Different contribution margins |
| New Management Hire | Higher cost and potentially greater capacity |
A monthly calculation may be useful during periods of rapid change.
For a more stable business, reviewing break-even after significant pricing, staffing, or cost changes may be enough.
Build a Simple Break-Even Dashboard
Break-even becomes more useful when it is viewed with a small group of related financial and operational metrics.
| Metric | What It Tells You |
|---|---|
| Break-Even Revenue | Revenue needed to cover included costs |
| Actual Revenue | Current sales performance |
| Contribution Margin % | Revenue remaining after variable costs |
| Average Job Value | Revenue generated per completed job |
| Break-Even Jobs | Approximate job volume required |
| Margin of Safety | Distance above break-even |
| Labor Cost % | Labor burden relative to revenue |
FIGURE 6 — BREAK-EVEN DASHBOARD
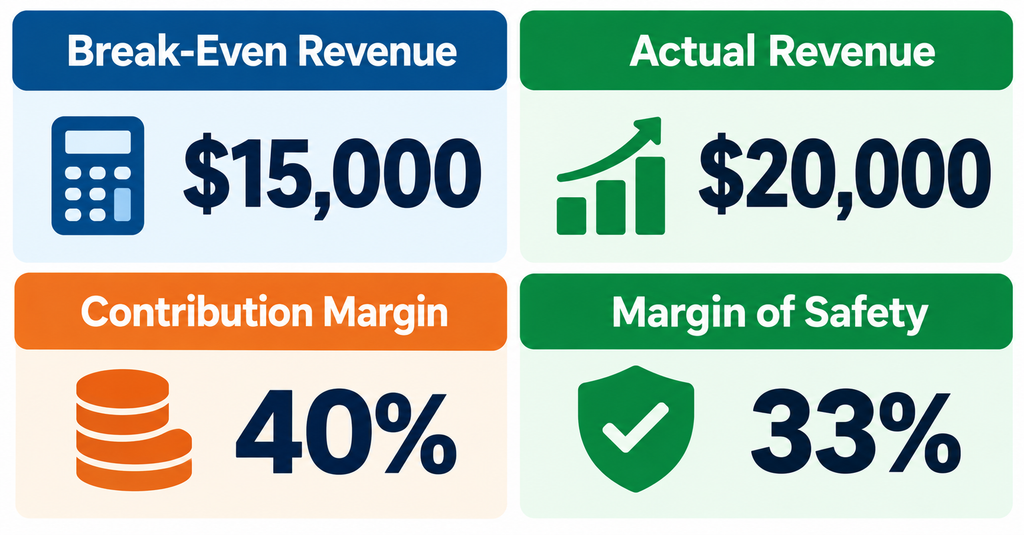
Do not try to maximize or minimize one metric in isolation.
The purpose of the dashboard is to show whether pricing, costs, job volume, and margins are working together to produce a financially sustainable business.
How to Lower Your Cleaning Business Break-Even Risk
You do not always need to reduce the break-even number itself.
A growing company may intentionally accept a higher break-even point when investing in capacity.
The more important goal is to maintain enough contribution and demand to operate safely above it.
| Lever | What to Change | Break-Even Impact |
|---|---|---|
| Improve Contribution Margin | Adjust pricing and control variable costs | More of each revenue dollar is available to cover fixed costs |
| Control Fixed-Cost Growth | Review recurring overhead before adding it | Prevents the monthly revenue threshold from rising unnecessarily |
| Increase Average Job Value | Improve pricing, packages, and appropriate add-ons | Fewer jobs may be needed to reach the required revenue |
| Protect Productive Capacity | Reduce travel, schedule gaps, callbacks, and rework | Helps available labor produce more revenue without simply adding jobs |
The best lever depends on what is driving your break-even point. If variable costs are the problem, focus on contribution margin. If overhead is rising, examine fixed costs. If job volume is already high, improving average job value or productive capacity may be more useful than simply chasing more bookings.
Know the Revenue Threshold Before You Chase Growth
More revenue does not automatically mean more profit.
Your break-even point gives you a baseline for understanding how much revenue the business needs before its cost structure is covered.
Start with realistic fixed costs and variable costs. Calculate your contribution margin. Convert the result into a revenue target and, when useful, an approximate job target.
Then monitor how pricing, labor, overhead, and service mix change that threshold over time.
The goal is not merely to reach break-even.
It is to build enough profitable revenue above it to create a cleaning business that can absorb normal fluctuations, invest in growth, and remain financially sustainable.